The ready-made meals market in Italy
In recent years, the ready-to-eat market for bars, pubs, and restaurants, as well as for private customers, has reached a turnover of several hundred million euros, approximately 390 million to be precise.
This has also led to a consequent increase in volumes, with a 6.9% increase in sales per package, for a total of 193.1 million packages sold.
Geographical Areas and Distribution Channels
The Northwest region is holding up the most geographically, accounting for 34.9% of the market and increasing by 10.1% in value and 6.3% per package. This is followed by the Northeast, which accounts for 25.8% of sales and recorded a 9.2% increase in value and 4.8% per package.
“Central and Southern Italy follow, with similar contributions to the performance,” shares Matilde Ciroldi of NIQ, “representing 22% and 17.3% of total turnover, respectively.
Among the distribution formats, supermarkets play a significant role, accounting for 40.4% of total turnover. Over the past year, this format exceeded €132 million, with growth of +11.2% in value and +6.3% per pack.
Within modern distribution, hypermarkets remain significant (+9.6% in value and +3% per pack), accounting for 24.1% of the market. Discount stores also make a significant contribution, a channel with a similar weight to hypermarkets (26%) and an increase of 10.7% in value and 11.1% per pack.”
Segment Trends
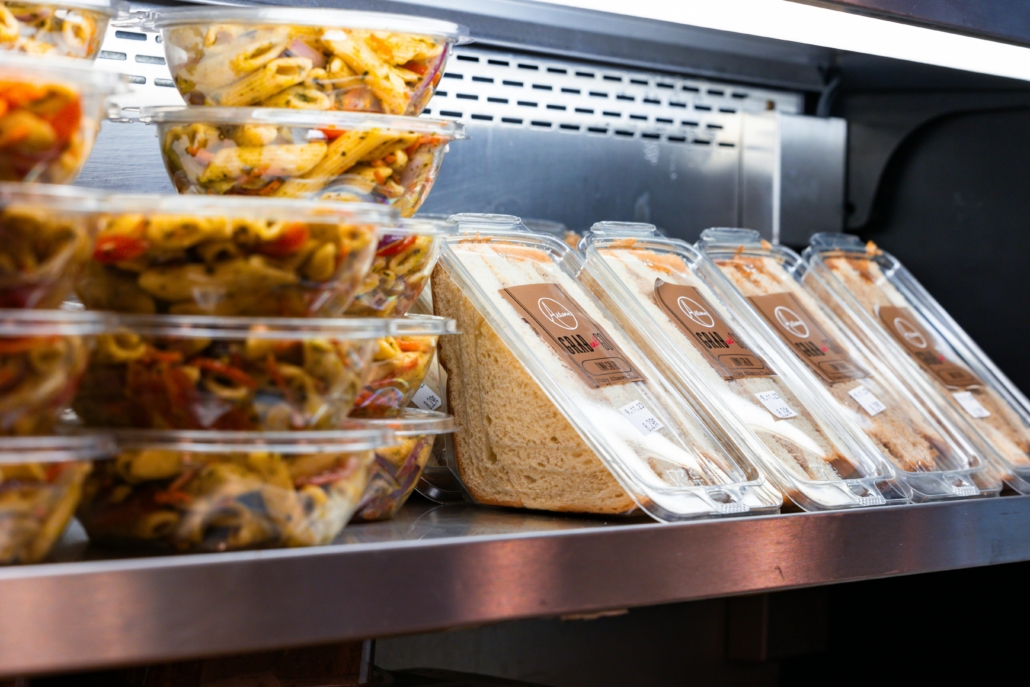
Within UHT ready meals, among the macro-segments, the largest contribution is made by other ready meals – a €74 million market – which in the last year grew by 20.1% in value and 12.2% per package thanks to the appetizers and salads sub-segment, which represents almost 17% of sales.
“Among the drivers that have driven this segment’s revenue growth (+30.4%),” Matilde Ciroldi continues, “is not only the increase in the average price for Italy as a whole (+10.6%, averaging €11.76/kg), but also the increase in promotional pressure, which has reached 28.1% for Italy as a whole, growing strongly across all modern distribution channels.
Beyond price and promotions, the increase in appetizers and salads is also due to the increase in offerings, i.e., the average number of items sold per store (4.1 for Italy as a whole, +0.6 points), especially in hypermarkets but also in supermarkets.
The second-highest contributor to performance is first courses (+6.3% in value and +5.5% in packs), which in the last year achieved a turnover of almost €210 million, primarily thanks to foreign specialties (+7.3% in value and +7.4% in packs). conf.), demonstrating that international and ethnic products no longer represent a trend, but a new eating habit of Italian consumers”
This post is also available in:


